Friday, April 1, 2022

Commentary for March, 2022

Hello all - we hope you had a nice March.

It was a remarkable turnaround for the markets, with stocks rising sharply in March.  The Dow rose by 2.2%, the S&P 500 gained 3.7%, and the Nasdaq, which has a high concentration of technology companies, was up 3.5%.

The end of March also means the end of the first quarter, which was the worst quarter in two years.   Over this period, the Dow fell 4.6%, the S&P lost 4.9%, and the Nasdaq suffered a 9.1% drop. 


Here’s a closer look at the markets this month:


While stocks were a big story, the bond market was an even bigger story this month.

Interest rates on bonds shot higher at a pace only seen two other times this century.


What this means is that our record low borrowing costs are rising very quickly.  A good example is mortgage rates.  It wasn’t long ago that average mortgage rates were below 3%, but they’ve very quickly jumped to almost 5%. 


This also means the bond holdings in your portfolio have quickly fallen in value.  When yields on bonds rise, their prices fall.  Below is one of the bond index ETF’s we use a lot - it’s easy to see how much the prices have fallen.


 _____
 
 
What caused the big swings in these markets this month?  

For the stock market, a lot of attention was focused on the fighting in Ukraine.  The outlook for the war improved as the month went on - whether that will turn out to be accurate or not remains to be seen - and it gave the markets a reason to rise.  Wars have historically seen stocks fall initially, but rally later.  That may be the case again here.  

On the other hand, the big moves in the bond market were largely driven by the Fed.  

The Fed held one of their policy meetings this month, where they announced an increase in interest rates.  This is the first increase since the pandemic struck, when they lowered rates as a form of stimulus to make borrowing easier.  Now they must raise rates to keep inflation from rising too high (although they are pretty far behind the curve here).


Investors see many more rate increases coming this year.  Current market projections show nine rate hikes of 0.25% this year, but there may be a few 0.50% rate hikes along the way. 


These projections have bond investors worried rates will keep rising and bond prices falling, which helped cause the sell-off in bonds we saw this month.

_____
 
 
On the topic of inflation, the CPI inflation metric again came in at the highest level in 40 years.


Inflation at the business level (the PPI) stands at its highest level ever.


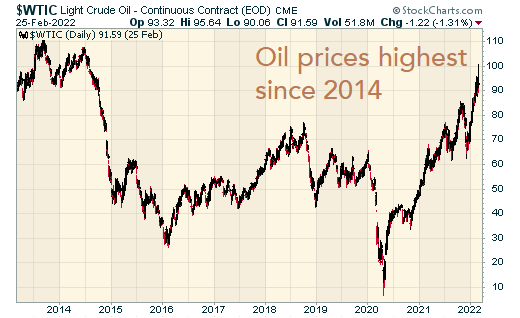
High oil and gas prices have played a large part in the increase in inflation.  In the chart below, we can see how oil prices have shot higher this year. 


Interesting to note, and probably not surprising, spikes in oil prices have often seen recessions follow. 


 _____
 
 
As for other economic data out this month, the manufacturing sector of our economy strengthened, but the service sector dropped sharply.


Retail sales were higher.


Durable goods - which are items with a longer life, like a phone or dishwasher - fell sharply last month. 


Sentiment among the public ticked higher:


On the other hand, small business owners are much less optimistic.


The same small business survey noted that more and more businesses are worried about rising inflation.


 _____
 
 
Where does the market go from here?

In the short term, we think the overall market looks a little expensive.  The month closed with some selling and we wouldn’t be surprised to see this continue.  It doesn’t look like a good time to put new money in the market in the short term.

We aren’t too optimistic on the longer term, either.  The days of the market steadily rising are probably over as the Fed removes more and more of its stimulus and economic growth slows.  There may be buying opportunities from time to time, but we think they will be short-lived.  


This commentary is for informational purposes and is not investment advice, an indicator of future performance, a solicitation, an offer to buy or sell, or a recommendation for any security. It should not be used as a primary basis for making investment decisions. Consider your own financial circumstances and goals carefully before investing. Past performance cannot guarantee results.

Tuesday, March 1, 2022

Commentary for February, 2022

Hello all - we hope your February was a nice one.

It wasn’t a great month for the markets, with the Dow lower by 3.5%, the S&P 500 lost 3.1%, and the Nasdaq, which has a higher concentration of technology companies, was down 3.4%.


February may be the shortest month, but it packed a lot of action into it.  

Stocks opened the month higher, but fell as it looked like the Fed was poised to pull back on their stimulus even more than expected.  Putin’s invasion into Ukraine caused even more selling.  Stocks posted a slight rebound late in the month as bargain-hunting investors tried to find some cheap deals. 


 _____
 
 
Russia was the big story this month, which shouldn’t be a surprise.  The markets have been very volatile this year and the Ukraine news kept that volatility high. 


In fact, the markets have been so volatile that the Nasdaq index even saw a 7% move in one day - that’s something that hasn’t happened since the financial crisis over a dozen years ago!


Commodities saw even more volatility than stocks.  With Russia being such a large oil producer, our already-high oil prices shot up to levels we haven’t seen since 2014.


Gold investors did well, though, as investors looking for safety found it in gold.


Not surprisingly, the Russian stock market fell sharply.


How much will this war impact our markets?  We still must see how much it escalates, but in reality, it will have little impact on our economy and our businesses.  For the companies in the S&P 500, only 1% of their revenue comes from either Russia or Ukraine.  

However, the commodity markets will see more of an impact.  Oil prices, as the earlier chart shows, will rise and so will our gas prices at the pump.  They are also big exporters of other commodities like wheat, so these products will also see higher prices.  

Overall, though, markets have historically moved higher during times of war (we think the decline in 2001 was more due to the dot-com bust at that time).  


 _____
 
 
While the war grabbed headlines, the Fed is still likely to have the biggest impact on our markets.  

The Fed has been widely expected to pull back on their stimulus and because inflation is so high, many investors believed the Fed will pull back significantly.  However, the war made a large pullback less likely and this news actually helped stocks rise at the end of the month.  

The chart below shows how much investors think the Fed will pull back on their stimulus.  Without going into the specifics of the chart, you can clearly see how it reversed course in February, indicating investors don’t think the Fed would pull back on their stimulus as much as originally believed. 


 _____
 
 
The economic data out this month was mostly poor.  

Inflation, again, was the big topic as the inflation levels remain high.  The consumer price index, or CPI, again hit its highest level in 40 years.


Inflation at the business level (the PPI) moved slightly lower last month, though it still remains very high. 


Small businesses are especially concerned with inflation.  Bigger companies are better able to raise prices to offset these higher costs, but its more difficult with small businesses.


Both the manufacturing and service sectors weakened for the second-straight month.


Retail sales were higher…


…but it may be that people are spending more because inflation is higher. 


Durable goods - which are items with a longer life, like a phone or dishwasher - keep rising. 


Sentiment among the general public is low and falling.


Small business owners are a little less optimistic.


 _____
 
 
Where does the market go from here?

Stocks look very oversold (cheap) and due for a rebound, but that doesn’t mean they can’t go lower as the Ukraine fight evolves.  As we discussed earlier, wars have historically been good buying opportunities.

We don’t think any rise will last long, though.  The days of the market steadily rising are probably over as the Fed removes more and more of its stimulus, economic growth slows, and the chance of a recession increases.  There may be buying opportunities from time to time, but we think they will be short-lived.  


This commentary is for informational purposes and is not investment advice, an indicator of future performance, a solicitation, an offer to buy or sell, or a recommendation for any security. It should not be used as a primary basis for making investment decisions. Consider your own financial circumstances and goals carefully before investing. Past performance cannot guarantee results.

Tuesday, February 1, 2022

Commentary for January, 2022

Hello all - we hope your year got off to a better start than it did for the markets.   

There’s an old saying on Wall Street that “as goes January, so goes the year.”  Let’s hope that’s not the case this year as stocks had their worst month since March, 2020, when the pandemic was in high gear.  

For the month, the Dow fell 3.3%, the S&P 500 lost 5.3% - its worst January since 2009 - and the Nasdaq, which has a higher concentration of technology companies, was down 9.0% - nearly its worst January ever.


Here’s a look at the three major indexes this month:


Although January was rough, it could have been worse.  The first three weeks were the worst EVER start to the year for the S&P 500. 


Needless to say, volatility picked up in a big way this month.  Stocks saw big swings every day - some days the market would be several percentage points higher to start the day, only to finish several percentage points lower (and vice-versa).  It’s very rare to see trading like this. 


 _____
 
 
So, what’s going on?  Why all the volatility?

It’s all about the Fed.

Really, it’s been all about the Fed for many years now.  They’ve printed so much money through their stimulus in order to keep interest rates low, and that’s flowed into the stock market and propped up stock prices.  

Bad news.  Good news.  It hasn’t mattered.  The stimulus is like a pain killer that keeps the market flowing higher.    

Take a look at stocks since 2008 - does this look like a normal market to you?


However, it’s clear the party is ending.  The high inflation levels are forcing the Fed to pull back on their stimulus and like a drug addict losing its fix, the markets are not happy about it.  

In early January, the minutes from their December meeting were released and they suggested the Fed would be more aggressive in pulling back the stimulus.  The markets weren’t happy, falling the most ever on a Fed minutes day.


Later in the month, the Fed held one of their policy meetings.  Again, the Fed showed it was willing to pull back on their stimulus even more than expected and stocks fell sharply on the news.


We think the massive amounts of selling we saw this month may have been an overreaction.  Yes, the Fed will pull back its stimulus soon, but historically, the markets tend to do fairly well until a few months into the reduction of stimulus.  Of course, this time could be different since we’re in unchartered territory and have never seen this amount of stimulus before.  

We’ll talk more about our outlook for the market later in this commentary.

_____
 
 
Switching gears, corporate earnings were in focus as results from the fourth quarter started coming in.

Earnings haven’t been too impressive, although only about a third of the companies in the S&P 500 have reported so far.  There have been a few standouts, like Apple and Microsoft, but many companies still have supply-chain problems and high inflation issues, but many see these problems fading later in the year.  

_____


As for economic data, we’ll start with what everyone’s talking about, and that’s inflation.

Inflation at the consumer level, the CPI, again hit its highest level in 40 years.


Inflation at the business level (the PPI) moved slightly lower last month, though it still remains very high. 


Small businesses are especially concerned with inflation.  Bigger companies are better able to raise prices to offset these higher costs, but its more difficult with small businesses.


Other economic data looks mixed.  Economic growth in the fourth quarter, measured by the GDP, was very strong.


However, both the manufacturing and service sectors weakened.


Retail sales turned lower:


While durable goods - which are items with a longer life, like a phone or dishwasher - keep rising. 


Sentiment among the general public took a turn lower…


While small business owners became a little more optimistic…


 _____
 
 
Where does the market go from here?

Stocks looked very oversold (cheap) late in the month and overdue for a rebound, which did appear the last two days of the month.  

Below is a big image with some of the indicators we follow, showing how oversold they were.  We won’t go into what the indicators are or how they work, but you can see they were at an extremely low level and that usually results in a rebound.


This commentary is for informational purposes and is not investment advice, an indicator of future performance, a solicitation, an offer to buy or sell, or a recommendation for any security. It should not be used as a primary basis for making investment decisions. Consider your own financial circumstances and goals carefully before investing. Past performance cannot guarantee results.